What is the scope and industry significance of the Anti Jamming Equipment Market?
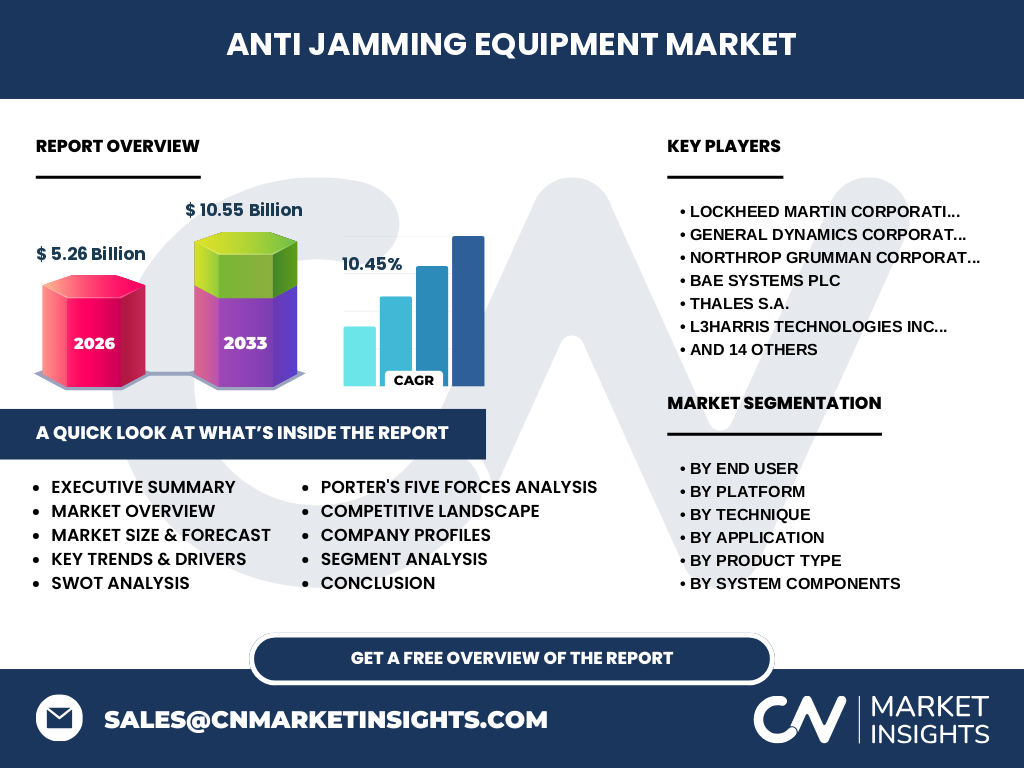
Our analysis indicates that the Anti Jamming Equipment Market represents a critical defense technology sector valued at 5.26 Billion in 2026. This domain encompasses specialized hardware and software designed to protect military and commercial navigation from electronic warfare threats, operating under stringent regulatory frameworks set by the FCC and international defense ministries.
Key market drivers, restraints, challenges, and opportunities shaping Anti Jamming Equipment Market
The market is propelled by escalating geopolitical tensions and GPS spoofing incidents targeting critical infrastructure. However, high development costs for advanced antenna arrays act as a restraint. Significant opportunities lie in upgrading legacy fleets with robust anti-jamming receivers to ensure uninterrupted Positioning, Navigation, and Timing.
Emerging trends and growth patterns in Anti Jamming Equipment Market
A notable industry trend is the rapid adoption of adaptive beamforming antennas and digital signal processing units to counter sophisticated barrage and deception jamming. Prime contractors are increasingly integrating machine learning algorithms into countermeasure systems to autonomously detect and mitigate interference in contested electromagnetic spectrums.
COVID-19 impact analysis and recovery trajectory
The pandemic caused temporary supply chain bottlenecks for critical semiconductor components and rare-earth materials used in power amplifiers and radio frequency filters. Despite these logistics hurdles, defense spending resilience ensured a swift V-shaped recovery, accelerating government investments in hardened electromagnetic protection devices.
Competitive Benchmarking and Industry Structure
Market concentration remains moderately high, dominated by aerospace and defense primes such as Lockheed Martin Corporation, Northrop Grumman Corporation, and BAE Systems plc. These tier-one suppliers leverage extensive R&D budgets to dominate the military segment, while specialized innovators focus on commercial telecommunications and maritime resilience.
Executive summary of key findings for the Anti Jamming Equipment Market
Our comprehensive assessment reveals a thriving sector projected to reach 10.55 Billion by 2033, expanding at a robust CAGR of 10.45% from 2027. Demand is heavily concentrated in defense and aerospace applications, driven by the imperative to safeguard autonomous platforms against advanced electronic attack vectors.
Market forecast from 2027 to 2033
The data projects consistent double-digit expansion, scaling from the 2026 baseline to 10.55 Billion by the end of 2033. This growth trajectory is underpinned by multi-year defense modernization contracts and the commercialization of resilient navigation terminals for autonomous air and ground vehicles.
Segmentation analysis across end users, platforms, and techniques
The sector breaks down by End User (Defense and Military, Aerospace, Government Agencies, Commercial Telecommunications, Maritime), Platform (Airborne, Ground, Naval, Space), and Technique (Nulling Systems, Beam Steering Systems, Excision Systems, Frequency Hopping). Defense applications capture the largest revenue share due to mandatory military standards.
Regional market analysis and geographic distribution
North America dominates global consumption due to high defense budgets and the presence of major innovators like L3Harris Technologies Inc. and General Dynamics Corporation. Meanwhile, the Asia-Pacific region exhibits the fastest growth, spurred by rising military expenditures and territorial disputes necessitating advanced surveillance and reconnaissance upgrades.
In-depth regional review of key markets
European markets are experiencing accelerated adoption under European Defence Agency initiatives, with firms like Thales S.A. and Leonardo S.p.A. spearheading anti-jamming integration. In the Middle East, high threat perception drives aggressive procurement of sophisticated shielding enclosures and null steering antennas for ground and airborne platforms.
Company profiles and strategic positioning
Industry leaders like Israel Aerospace Industries Ltd. and Elbit Systems Ltd. excel in combat-proven electronic countermeasure systems. Simultaneously, commercial-focused entities such as Trimble Inc. and Furuno Electric Co. Ltd. adapt military-grade technologies for maritime and commercial aviation navigation security.
Porter's Five Forces analysis of competitive intensity
Supplier power is moderate, constrained by specialized semiconductor and filter manufacturing requirements. Threat of new entrants remains low owing to high barriers to entry, stringent certification hurdles, and massive capital expenditure needed for advanced electromagnetic testing facilities.
SWOT analysis of the Anti Jamming Equipment sector
Key strengths include proprietary antenna design and high reliability in hostile environments. Weaknesses involve complex integration cycles. Opportunities abound in autonomous vehicle protection, while threats stem from rapid technological advancements in adversarial electronic warfare capabilities.
Value chain analysis from raw materials to end-users
The value chain originates with raw material suppliers providing gallium arsenide and specialized ceramics for radio frequency filters. Mid-stream manufacturers assemble signal processing units and controlled reception pattern antennas, culminating in delivery to defense agencies and system integrators.
Investment insights and strategic recommendations
Investors should target niche innovators specializing in multi-frequency receivers and spoofing detection systems. Strategic partnerships with established defense primes offer the most viable pathway for small-to-medium enterprises to commercialize breakthrough protective hardware.
Conclusion and key takeaways for stakeholders
The Anti Jamming Equipment Market offers exceptional growth potential, backed by a projected 10.45% CAGR through 2033. Stakeholders must prioritize R&D in adaptive beamforming and software-defined mitigation to capture high-value defense and aerospace contracts.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining defense trade registry data, primary stakeholder interviews with chief technology officers, and secondary macroeconomic indicators from global defense expenditure reports to ensure high fidelity and market accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics across specified product types, including anti-jamming antennas, receivers, system components, and protective hardware. Excluded from this scope are legacy analog communication systems predating modern digital signal processing standards.
Recent developments, partnerships, and strategic moves
Recent industry momentum features major contract awards to companies like ASELSAN and HENSOLDT AG for advanced countermeasure systems development. Strategic mergers and acquisitions continue to reshape the landscape as major aerospace firms acquire specialized anti-jamming antenna startups.